Story No. 2 · Frankfurt · Single, around €120k
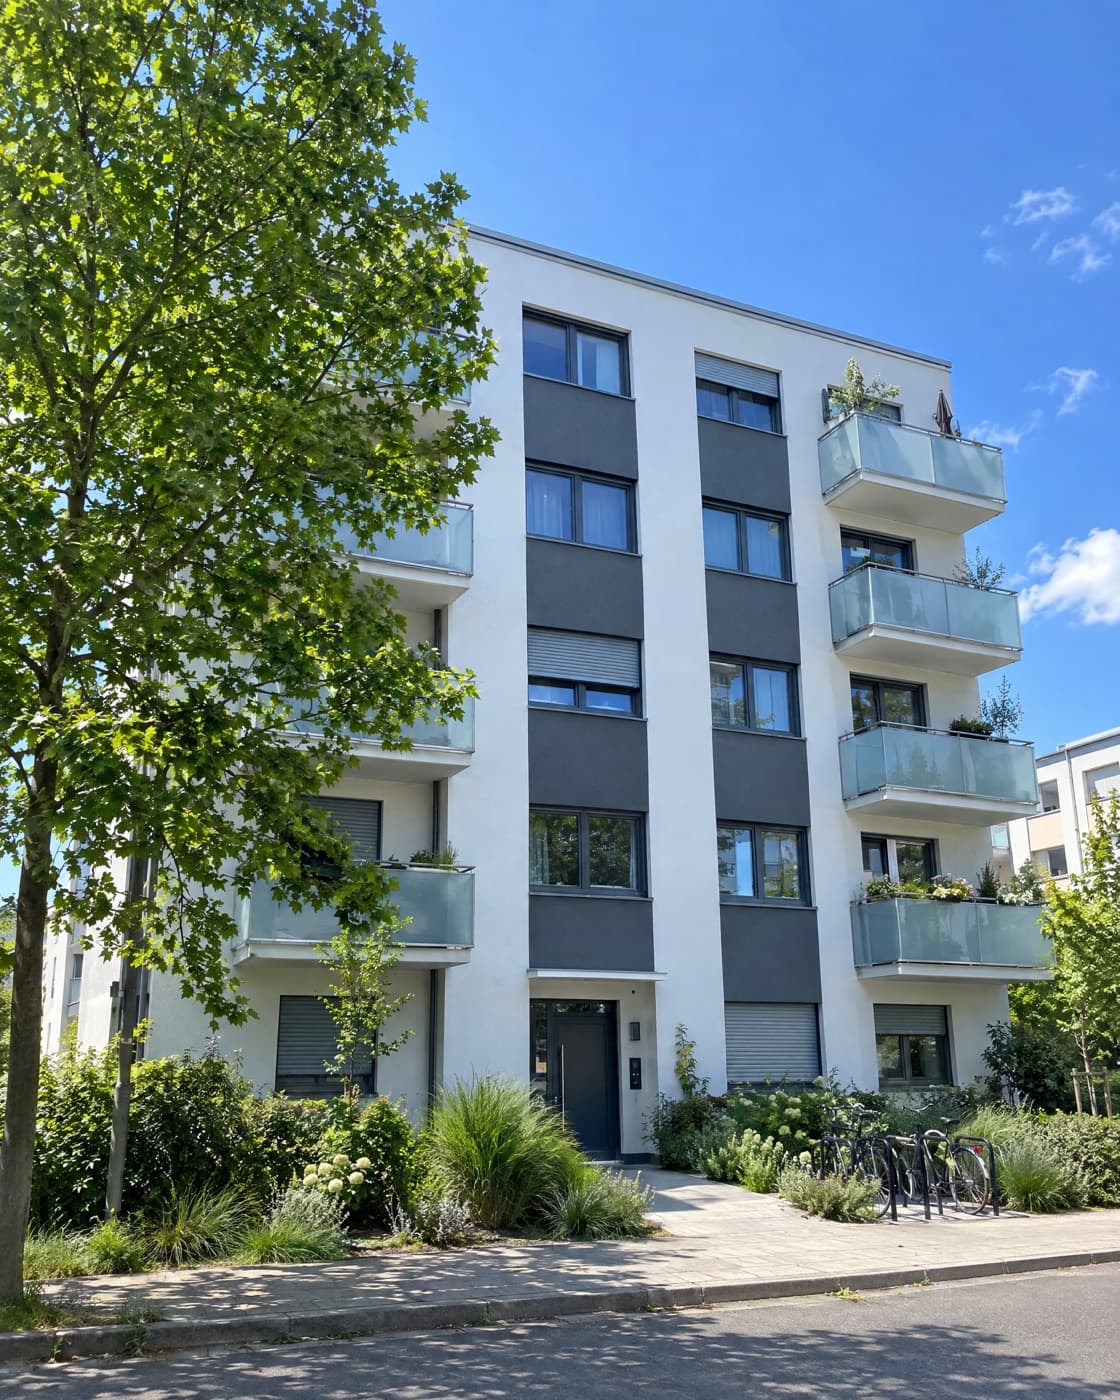
A new-build in Frankfurt Gallus, bought for the tax effect as much as the rent.
Single, around 120.000 € a year, and paying the marginal tax rate that comes with it. The question that brought this buyer to Financemate is the one most people in that bracket ask sooner or later: what does a rented apartment do to my tax bill, and does the rent cover the rest?
The whiteboard calculation with Karim walked through financing, the 5 % degressive depreciation a 2026 new-build qualifies for, and the exit. Only then did Sven bring tool candidates.
The one that made it: a 59 m² new-build in Frankfurt Gallus, completed 2026, 100 % financed at 4,6 % fixed for ten years.
The people on this deal
Two people carried it from the first call to the notary.
Financemate expert
Karim Beltaji
Co-Founder
Spent years in finance before building the company he wished had existed for internationals like him.
On this deal
Walked the numbers in the whiteboard calculation and through every scenario before the buyer signed.
Property partner
Sven
Real estate partner
More than 20 years in real estate and an active property investor himself. Sources and evaluates off-market projects for the Financemate network and supports buyers through to the notary and the bank.
On this deal
Sourced the apartment, took care of the financing, and stays on as investment mentor till the notary.
The goals
The brief, before any listing was opened.
What the buyer wanted going in. Every scenario below was tested against it.
- 01
Put a 120.000 € salary to work against the tax bill
About 66.500 € of income tax saved over ten years, on the assumptions below.
- 02
A new-build that qualifies for degressive depreciation
Completed 2026, so the building depreciates at 5 % degressively from year one.
- 03
Rent that covers most of the loan from day one
26 € per m² covers about 80 % of the loan payment in 2027; the tax refund covers the rest.
- 04
Sell tax-free after ten years, or keep it
Both were tested: a sale in 2036, and a 15-year hold through a rate jump.
The deal
What was bought, and on what terms
Frankfurt Gallus, 59 m², new-build 2026. Bought for 420.000 €, financed 100 % at 4,6 % fixed 10 y, against a 120.000 € income, with 33.600 € of the buyer’s own money.
Rent 26 € / m²·Repayment 1 %·AfA 5 % degressive·Appreciation 3 %·Income growth 0 %
Own capital covers the purchase costs only: 6 % transfer tax, 1,5 % notary and land registry, 0,5 % financing costs. Hessen, single filing.
- Worst month before tax benefits
- −470 €
- In 2027, narrowing every year as rent rises
- After tax benefits, first full year
- +294 € / month
- The apartment carries itself from year one
- Total wealth if sold in 2036
- 221.309 €
- 6,59× own capital · 20,7 % annualized
Projection from the assumptions above. Rent is indexed 2 % a year, the salary stays flat, the building is depreciated at 5 % degressively, and the apartment is sold after the 10-year holding period, so the gain is tax-free.
What we stress-tested
Click a column to see its charts- Total wealth at sale
- 221.309 €sold 2036
- Own capital multiple
- 6,59×20,7 % a year · 10 years
- Cashflow before tax benefits
- −40.162 €over the hold
- Cashflow after tax benefits
- +26.401 €over the hold
- Tax benefits over the hold
- +66.563 €10 years
Base case, year by year
Cashflow before tax benefits
per month · rent minus loan and costs
−40.162 €
Cashflow after tax benefits
per month · including the tax refund
+26.401 €
Tax impact
per year · income tax saved
+66.563 €
2026 is a part year. The purchase closed in Jun 2026, so those 7 months of ownership carry a full calendar year of tax effect, and the first bar sits far above the years that follow.
The same three charts every client sees for their own property in the Financemate scenario planner.